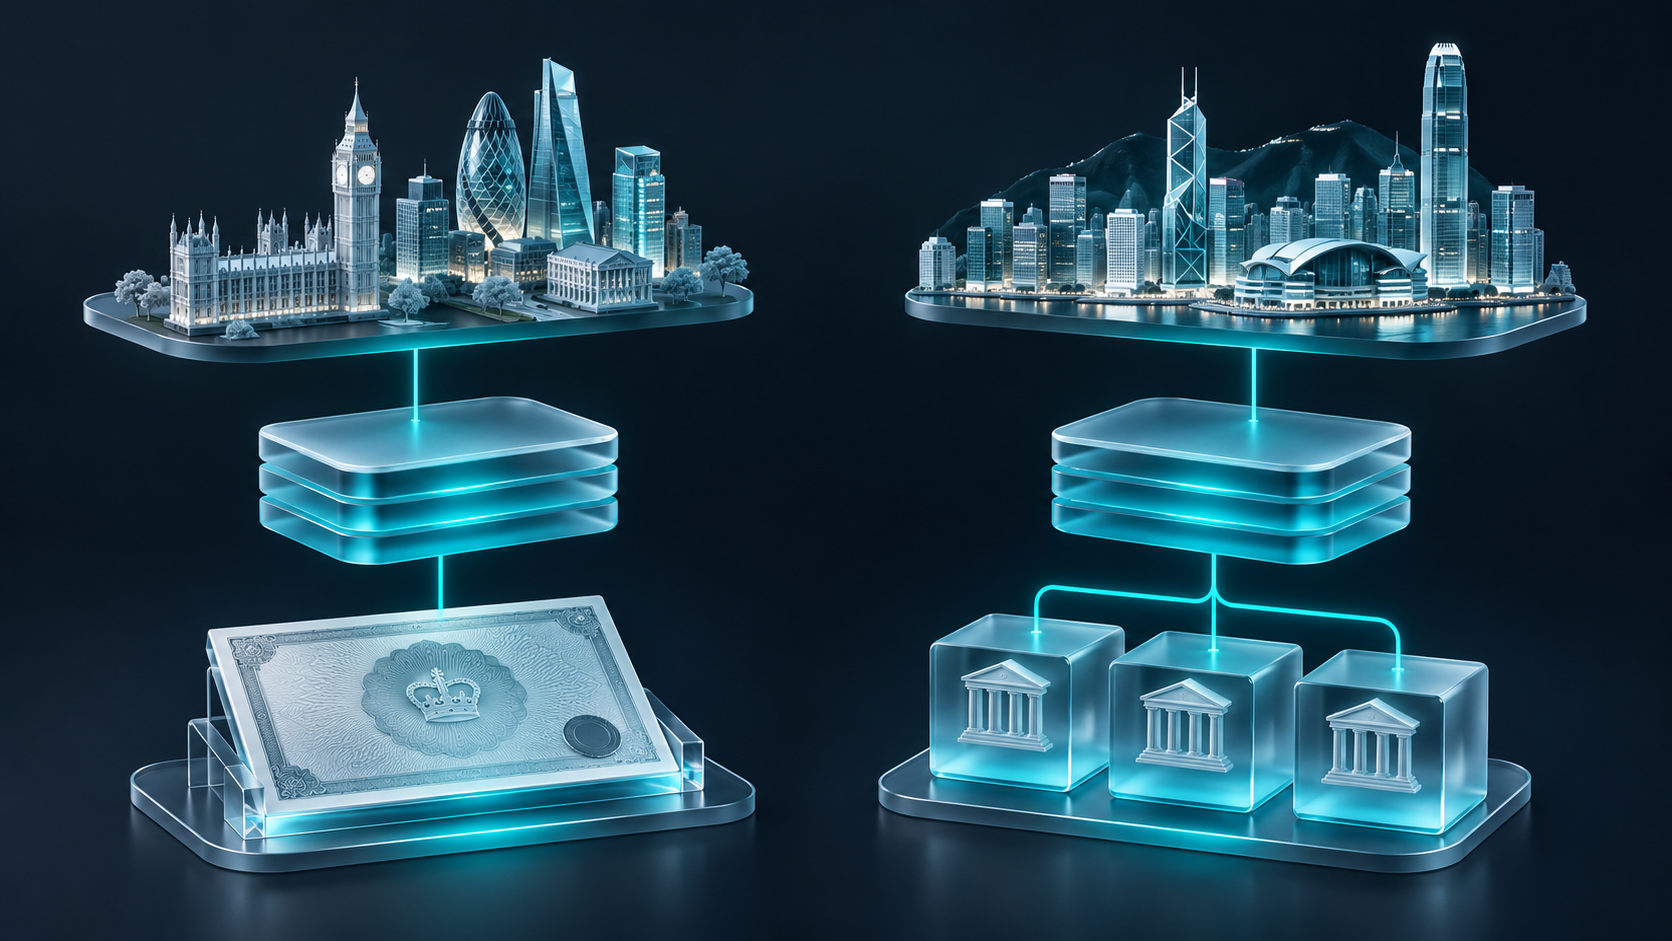
The UK is preparing a digitally native government bond. Hong Kong is testing round-the-clock settlement for tokenized deposit transactions. Both projects use tokenization, but they solve different problems.
On 2 November 2026, the UK government provided an update on its planned Digital Gilt Instrument, or DIGIT. The same day, the Hong Kong Monetary Authority announced a new phase of EnsembleTX, its tokenization pilot. Neither announcement means that a national bond market or an entire banking system has moved onto a public blockchain. UK government · HKMA
UK: a government bond built for digital infrastructure
A conventional gilt is a debt instrument issued by the UK government. Investors lend money to the government under the terms of the security. DIGIT is a planned digitally native gilt intended to test how distributed-ledger infrastructure can support issuance and settlement.
The November update described roles for HSBC Orion and LSEG's B3 digital securities infrastructure. The Bank of England approved a link between the two digital securities depositories, allowing participants to access the issuance through the connected arrangements. The government expects the pilot by the first quarter of 2027; that is a target, not proof of a completed issuance.
The connection is the interesting detail. Financial markets already depend on institutions that maintain records and facilitate settlement. If a digital bond requires everyone to use one isolated system, the operational benefits may be limited. Linking approved infrastructures tests whether participants can work across them.
The announcement does not establish how large the eventual issue will be or prove that a digital gilt is cheaper for investors. Those questions require results from the actual pilot.
Hong Kong: settling tokenized deposits around the clock
EnsembleTX is the pilot phase of Hong Kong's Project Ensemble. The HKMA says the latest phase supports 24/7 interbank settlement of tokenized deposit transactions using tokenized central bank money.
The distinction between the two types of money is important. A tokenized deposit represents a deposit relationship with a commercial bank. Tokenized central bank money, in this context, is used in the interbank settlement arrangement described by the HKMA. Their roles and claims are not interchangeable. HKMA release
The operational question is whether institutions can move assets and payment obligations through compatible systems outside conventional business hours. The announcement describes a pilot with participating institutions; it does not show that all banks or all customers have received 24/7 tokenized settlement.
A bond, a deposit and a stablecoin are different products
| Instrument | What it represents | Question to ask |
|---|---|---|
| Digital government bond | A government debt security issued or recorded using digital infrastructure | What are the security's legal terms and settlement arrangements? |
| Tokenized bank deposit | A deposit claim associated with a commercial bank | Which bank owes the deposit and who can use it? |
| Stablecoin | A token designed to track a reference value under its issuer's model | What backs it, who can redeem it, and on what terms? |
Tokenization describes a way to represent or manage something digitally. It does not make these instruments economically or legally equivalent. A tokenized bond remains a bond; a tokenized deposit does not automatically become a publicly transferable stablecoin.
Why financial institutions are interested
The potential attractions include shared records, faster reconciliation, programmable workflows and longer operating hours. In principle, settling a tokenized asset against a compatible payment instrument could reduce the gap between delivery and payment.
Those benefits depend on the system design and its users. A ledger cannot by itself remove legal disputes, credit risk, cyber risk, or the need to connect with existing banks, custodians and regulations. A controlled pilot can test a workflow without proving that it scales across an entire market or lowers costs.
The two projects are also independent. The UK announcement does not establish a direct DIGIT connection to Hong Kong's EnsembleTX. Their value as a comparison lies in the different layers they test: a government security and the settlement of tokenized deposit transactions.
What would count as progress?
For DIGIT, watch for the actual issuance, its size, investor access and details of how the connected depositories operate. For EnsembleTX, watch for repeat transactions, participating institutions, supported assets and evidence of performance beyond a demonstration.
The broader story is not simply that governments have discovered blockchain. It is that public authorities and financial institutions are testing which parts of existing financial infrastructure can change — and which legal and operational responsibilities still need to remain.
Based on announcements available on 9 November 2026. Both initiatives are pilots or planned pilot activity; timelines and implementation can change.